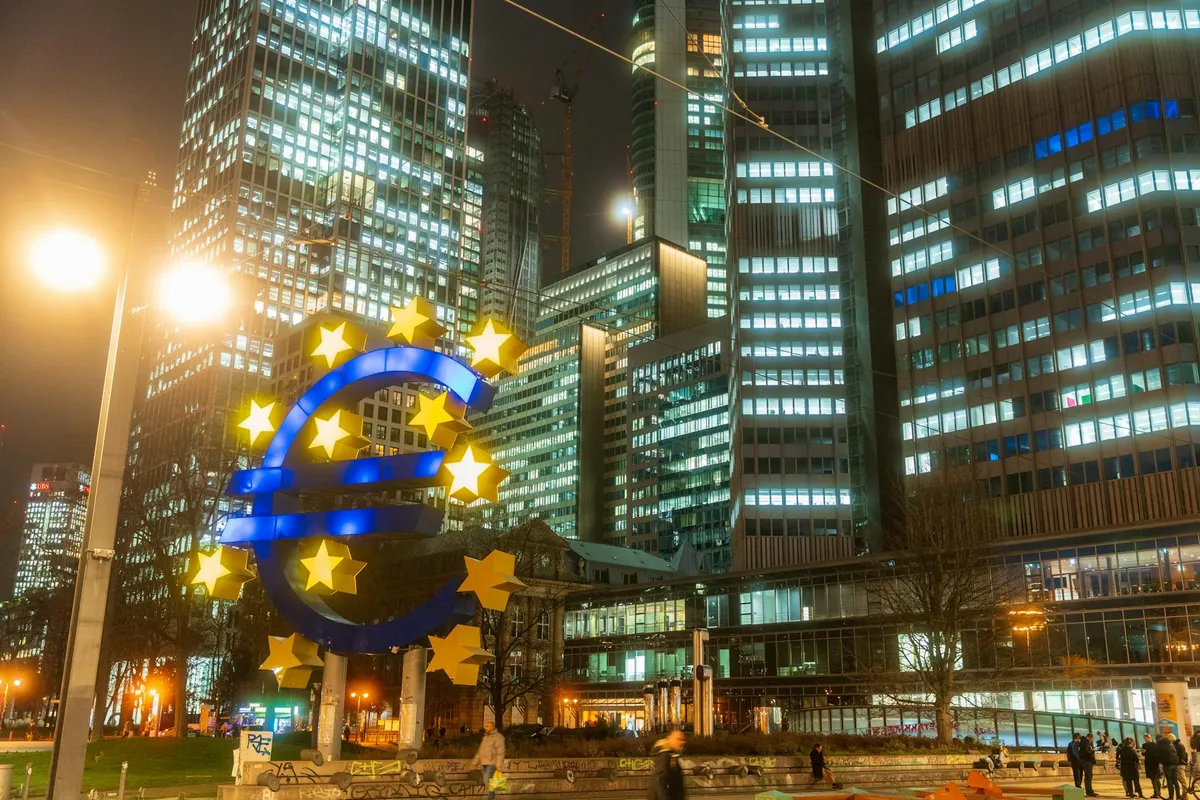
The European financial framework substantially shapes German markets through ECB monetary policy, EU regulatory directives, ESMA coordination, and broader European integration. Understanding the framework clarifies substantial portions of what German market participation involves and what continues to evolve.
This essay attempts to examine the European framework with the care it warrants. The reading rewards sustained attention to multiple institutional layers.
The basic European institutional structure
European financial framework operates through several major institutions:
European Central Bank (ECB): conducts monetary policy for euro area, including Germany. Operates Single Supervisory Mechanism for largest euro area banks.
European Commission: proposes EU legislation including financial regulation directives.
European Council and EU member states: adopt financial legislation following established processes.
European Securities and Markets Authority (ESMA): coordinates securities regulation across member states.
European Banking Authority (EBA): coordinates banking regulation.
European Insurance and Occupational Pensions Authority (EIOPA): coordinates insurance regulation.
Single Resolution Board (SRB): handles bank resolution at European level.
European Court of Justice: interprets EU financial law in disputes.
The institutional structure reflects substantial European integration with specific national autonomy preserved.
The ECB monetary policy dimension
ECB monetary policy substantially affects German markets:
Interest rate decisions affect German equity and bond markets.
Quantitative easing programs have substantial effects on German bond markets and broader asset prices.
Specific recent policy responses to inflation have substantially affected German financial conditions.
Forward guidance affects market expectations and pricing.
Specific ECB communications produce substantial market reactions.
The monetary policy dimension is substantial factor in German market behavior.
The ECB banking supervision
ECB banking supervision through Single Supervisory Mechanism affects German banking:
Largest German banks are directly supervised by ECB.
Smaller German banks remain supervised by BaFin with ECB oversight.
Specific supervisory standards apply across euro area banks.
Substantial supervisory capability concentrated at European level.
Coordination between ECB and BaFin affects practical supervisory activity.
The supervision dimension substantially affects German banking sector.
The EU directive framework
EU directives substantially shape German financial regulation:
MiFID II/MiFIR for securities markets and investment services.
UCITS Directive for retail investment funds.
AIFMD for alternative investment funds.
Solvency II for insurance regulation.
CRR/CRD IV+V for banking capital requirements.
Bank Recovery and Resolution Directive for resolution framework.
Specific other directives affecting various aspects of finance.
The directive framework creates substantial common European financial regulation.
The MiFID II framework specifically
MiFID II warrants specific examination as substantial framework for retail trading:
Comprehensive regulation of investment services across EU.
Specific requirements for investor protection including suitability, appropriateness, and disclosure.
Specific transparency requirements for markets and trading.
Specific product governance requirements affecting what products can be marketed to which investors.
Cost transparency requirements substantially changing how investment costs are disclosed.
Specific research separation requirements affecting investment research.
Continued evolution including MiFID III/MiFIR review.
The framework substantially shapes German retail trading environment.
The MiCA framework
Markets in Crypto-Assets (MiCA) regulation has emerged as substantial new framework:
Comprehensive EU-wide cryptocurrency regulation.
Specific licensing requirements for crypto-asset service providers.
Specific consumer protection requirements.
Specific stablecoin regulations.
Implementation across member states ongoing.
The framework illustrates EU's approach to emerging financial categories.
The ESMA coordination role
ESMA provides substantial coordination function:
Common technical standards across EU.
Specific guidelines on regulatory implementation.
Specific direct supervisory powers in defined areas.
Coordination of national regulators including BaFin.
Specific crisis response capabilities.
Continued evolution of ESMA's role over time.
The coordination supports common European approach while preserving national implementation.
The Banking Union
European Banking Union represents substantial integration:
Single Supervisory Mechanism for banking supervision.
Single Resolution Mechanism for bank resolution.
European Deposit Insurance Scheme (proposed but not yet implemented).
Substantial integration of euro area banking framework.
Specific German implications including how German banks operate within Banking Union.
Continued evolution including ongoing debates about completing Banking Union.
The Banking Union substantially affects German banking sector dynamics.
The Capital Markets Union
Capital Markets Union represents ongoing initiative:
Goal of integrating EU capital markets more fully.
Specific initiatives including securitization framework, retail investment strategy, listing reform.
Continued political and technical work toward implementation.
Substantial implications for German markets if Union progresses substantially.
Specific German interests including retaining Frankfurt as major financial center.
The initiative continues to develop with specific implementation patterns.
The European deposit guarantee framework
Deposit guarantee operates within European framework:
EU Deposit Guarantee Schemes Directive provides minimum protections.
German Einlagensicherungsfonds operates German framework within EU directive.
Cross-border depositor protection through specific arrangements.
Continued evolution including EDIS proposals.
The framework affects how German bank deposit protection operates.
The European tax dimension
European tax framework affects German finance:
EU directives on financial transactions and instruments.
Specific anti-tax-avoidance frameworks.
VAT treatment of financial services.
Specific cross-border tax issues.
Continued tax harmonization initiatives.
The tax dimension substantially affects German financial activity economics.
The Brexit effect
Brexit has had substantial European financial framework implications:
Substantial financial activity moved from London to EU centers including Frankfurt, Dublin, Paris, Amsterdam.
Specific market structures adjusted to post-Brexit reality.
Continued framework evolution addressing Brexit implications.
Specific German benefits from substantial activity relocation to Frankfurt.
Continued cross-border arrangements with UK affecting specific activities.
Brexit substantially affected European financial framework dynamics.
The sustainable finance framework
European sustainable finance framework has emerged as substantial new dimension:
EU Taxonomy Regulation defining sustainable economic activities.
Sustainable Finance Disclosure Regulation requiring specific ESG disclosures.
Corporate Sustainability Reporting Directive expanding sustainability reporting.
Specific implementation across financial sector.
Substantial implications for German financial activity.
Continued evolution as framework develops.
The sustainable finance framework illustrates how European framework continues expanding.
What the framework means for German participants
For German financial market participants:
European framework provides substantial common rules across EU.
Specific German implementation operates within European framework.
Cross-border activity benefits from European integration.
Specific protections operate at European and German levels.
Continued framework evolution affects ongoing market realities.
Substantive engagement with framework supports informed market participation.
What the framework means for cross-border activity
For cross-border financial activity:
EU passporting allows specific activities across member states.
Specific regulatory recognition supports cross-border services.
Specific common standards reduce friction.
Specific national particularities still require attention.
Continued integration trends affect future cross-border activity.
What the framework doesn't do
To be clear about limits:
European framework doesn't eliminate national differences. Substantial national autonomy remains.
Framework doesn't guarantee market outcomes. Markets remain markets.
Framework doesn't prevent all financial issues. Specific gaps and failures occur.
Framework doesn't fully integrate financial markets. Capital Markets Union remains incomplete.
Framework doesn't resolve all institutional questions. Continued evolution reflects ongoing development.
What the framework continues to evolve
Specific framework evolution continues:
Capital Markets Union continued development.
Banking Union completion debates.
MiFID III/MiFIR review.
Sustainable finance framework expansion.
Crypto framework implementation and refinement.
Retail investment strategy implementation.
Continued integration alongside continued national autonomy.
The evolution reflects ongoing European financial integration project.
What sustained attention reveals
The patient examination of European framework reveals substantial substantive material:
The framework is substantial and reflects substantial European integration.
Specific institutional features matter for participant decisions.
Continued evolution affects ongoing market realities.
Substantive engagement requires sustained attention to multiple institutional layers.
Cross-jurisdictional comparison clarifies what is distinctively European.
What this analysis suggests
The analysis suggests specific things:
European framework warrants substantive engagement rather than surface awareness.
German market participation requires understanding European institutional context.
Continued framework evolution warrants continued analytical attention.
Generic financial education adapted for German market misses substantial substantive material about European framework.
Substantive analysis benefits from sustained attention to multiple institutional layers.
What I would tell market participants
For German market participants:
Engage with European framework as substantial reality rather than as bureaucratic detail.
Understand how European-level decisions affect German market activity.
Recognize ongoing framework evolution affecting market realities.
Use substantive sources including official EU and ECB publications.
Maintain awareness of cross-jurisdictional implications of activities.
What this site continues to attempt
This site continues substantive analysis of European framework affecting German markets.
The work attempts to engage with framework as substantial reality rather than reducing to surface coverage.
The contribution is modest. The audience for substantive European framework analysis in English is small.
For readers interested in German markets: European framework awareness substantially improves market understanding.
For readers interested in European institutional development: financial framework offers specific case study of European integration.
The honest conclusion
The European financial framework substantially shapes German markets through multiple institutional dimensions.
Sustained attention reveals substantive material that surface coverage rarely captures.
The framework continues to evolve, requiring continued analytical attention.
For substantive market participation: European framework awareness substantially supports informed engagement.
For policy understanding: European framework offers specific case study of supranational financial integration.
For institutional analysis: framework reflects substantial integration project with continued evolution.
The framework continues. The integration continues. The substantive analysis warrants continuing.
That is the case for sustained engagement with European framework affecting German markets.